★★★★★
“When our insurance only wanted to give us a partial roof replacement she helped us with an appeal and was able to get a full roof replacement, paint and gutters!”
First-time homeowner · Google review, Feb 2026
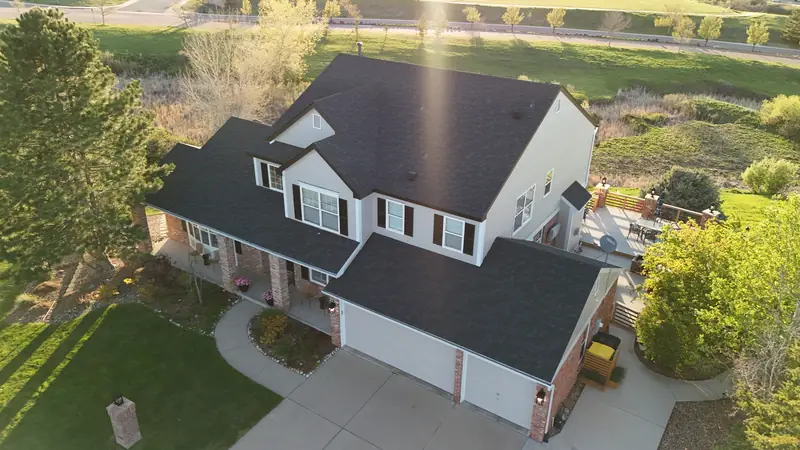
Denied & low roof claims · Colorado
We re-inspect for free, document what the adjuster missed, and send your insurer the evidence through supplements, and explain appraisal if it comes to that. You stay in control of your claim the whole way.
Why roof claims get denied
Most denials and lowball estimates fall into a few buckets. Knowing which one you’re in tells you what to do next.
The adjuster calls hail bruising age or granule loss. Close-up photos and test squares can show impact damage that age doesn’t explain.
Some policies exclude cosmetic damage, especially to metal. Whether damage is cosmetic or functional is often the real argument.
The claim gets tied to a storm that didn’t hit your area, or is called too late. We match damage to NOAA-recorded storm dates. See hail history.
The estimate only counts a few shingles. Once missed items are added, the total often clears the deductible.
The insurer approves one slope. Many cities don’t allow mixed shingles on a slope, and discontinued shingles can’t be matched.
Gutters, downspouts, vents, screens, paint, fences, and garage doors left off the estimate. On one Homey claim, those items took it from $2,281 to $58,171.
Your options, in order
Start at step one. Most claims get fixed by step three. Appraisal is there when the gap is big.
The denial letter, the adjuster’s estimate, your policy, and your declarations page. Text us photos of them. That’s enough for us to tell you where you stand.
We go over the roof, gutters, siding, paint, and windows with detailed close-up photos, and line up the damage with the storm date on record.
We meet your adjuster on the roof and submit a line-item supplement for what was missed. Many claims get corrected here.
If you agree it’s covered but not on the amount, most policies allow appraisal: each side picks an independent appraiser and an umpire settles the rest. We supply the documentation and walk you through it.
If an insurer isn’t responding or following its own policy, you can file a complaint with the Colorado Division of Insurance.
For coverage fights or unreasonable delays, a licensed public adjuster or an attorney may be the right call. We’ll tell you honestly when that’s the case.
Real results
Documenting missed damage is a normal part of our week, not a special project.
A real Homey claim
A Colorado Springs homeowner’s insurer first offered $2,281.80. Homey’s full inspection documented the roof, gutters, downspouts, exterior paint, and fence damage, and the claim was approved for $58,171.79.
Every claim is different. Coverage depends on your policy and your insurer.
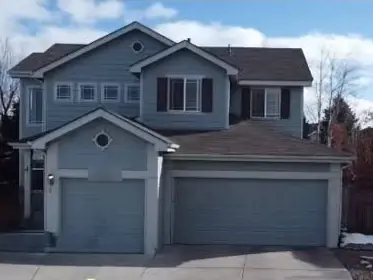
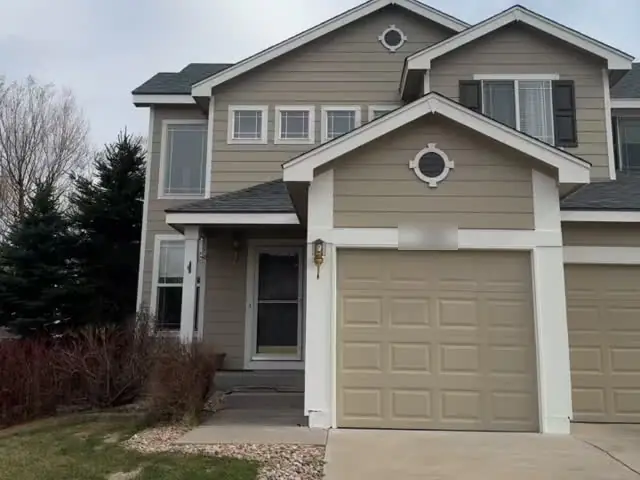
Real Homey jobs, from our Instagram. House numbers blurred.
A second Homey claim · From our Instagram
In Homey’s own words, as posted:
after: new roof, new dark gutters & downspouts, exterior paint
From our Instagram → Every claim is different. Coverage depends on your policy and your insurer.
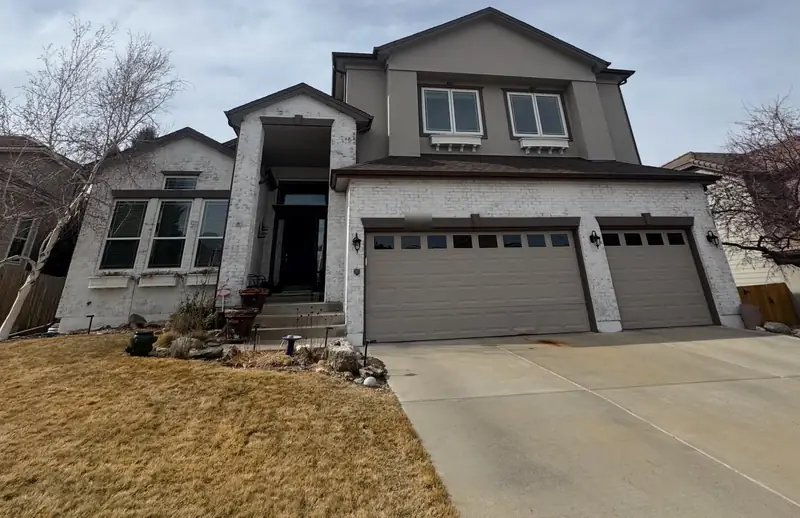
“Initially… they said we only qualified for a partial roof and partial paint… we were actually able to get full approval.”
“When our insurance only wanted to give us a partial roof replacement she helped us with an appeal and was able to get a full roof replacement, paint and gutters!”
“While the insurance company gave us a run for our money Allie stayed the course with me and pushed for what was right. I sincerely appreciate all of her hard work and efforts.”
“She managed communication with the insurance adjuster and kept me informed about timelines/expectations. She even came back afterwards to look things over with me.”
Colorado law
Colorado’s roofing contractor law protects homeowners on insurance jobs. Here’s what it says, and how we work within it.
Sources: Colorado Roofing Contractor Law (C.R.S. 6-22). General information, not legal advice.
Replacing the roof anyway? What Colorado’s new FORTIFIED roof law means for your insurance →
Denied claim FAQ
Text a photo of your letter to (720) 948-5726 and we’ll take a look.
Often not. Denials are frequently based on a short inspection, a wrong storm date, or calling hail damage “wear and tear.” A re-inspection with clear documentation, a supplement, or appraisal can change the outcome. Start by getting the denial and the adjuster’s estimate in writing.
Many homeowner policies let either side demand appraisal when you agree damage is covered but disagree on the amount. Each side picks an independent appraiser, and an umpire settles what they can’t agree on. Appraisal decides how much, not whether the damage is covered. Read your policy for the exact terms.
Colorado law doesn’t allow roofing contractors to act as public adjusters. Once you’ve signed with us, the law does let us discuss the scope of repairs with your insurer. We document the damage, write supplements, and meet your adjuster, and you stay in control of the claim.
Colorado law (C.R.S. 6-22-104) lets you cancel an insurance-funded roofing contract within 72 hours of getting written notice that the claim was denied in whole or in part, with deposits returned within 10 days. Your contract should spell this out.
Nothing. The re-inspection is free, and we’ll tell you honestly if we don’t think the denial is worth a second look.
Sometimes. Licensed public adjusters can negotiate your claim for a percentage, and attorneys handle bad-faith and coverage disputes. If your case needs one, we’ll tell you. This page is general information, not legal advice.
Colorado rulings & rules
In BonBeck Parker v. Travelers (10th Cir. 2021), applying Colorado law, the court held that "amount of loss" in that policy's appraisal clause includes causation disputes, so appraisers could decide whether hail caused the disputed roof damage.
Source: BonBeck Parker, LLC v. Travelers, 14 F.4th 1169 (10th Cir. 2021)
In Bertisen v. Travelers (D. Colo. Sept. 8, 2023), a federal judge read an ambiguous policy in the homeowners' favor and held that it covered matching on a concrete tile roof.
Source: Bertisen v. Travelers Home & Marine, No. 20-cv-03650 (D. Colo.)
DOI Bulletin B-5.57 (effective March 16, 2026) says aerial imagery shouldn't be the sole basis for adverse actions such as nonrenewals or claim reductions. Separately, C.R.S. 10-4-110.7 requires 60 days' mailed notice, with reasons, before a homeowners nonrenewal.
Source: DOI Bulletin B-5.57 · C.R.S. 10-4-110.7